Resources

Our research, in public.

Company analyses produced by the Shydel Agent on real names: a video walkthrough of each thesis and the slide deck behind it. These use our general value rubric; for a client we build the same work on the firm's own rubric.

Videos.

Each one walks through the score, what a share is worth, the risks, and the decision.

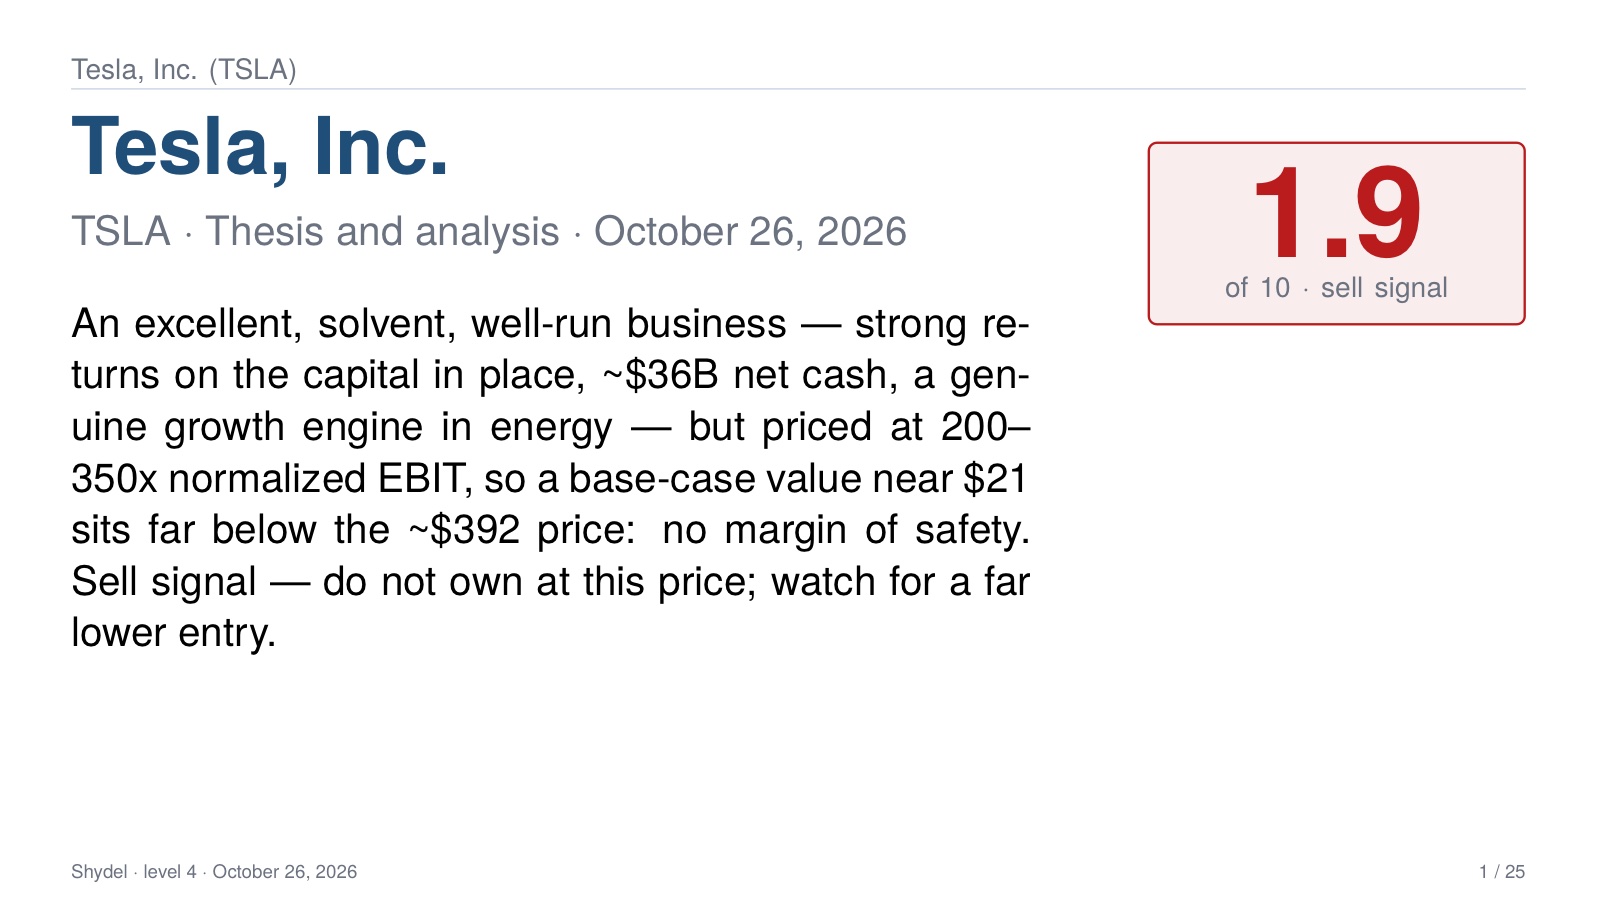
TSLA · TeslaSell

A good business at 200x operating profit.

About $36 billion of net cash and an energy segment growing fast, but automotive is 86% of revenue and shrinking, the operating margin has fallen from 16.8% to 4.6%, and the base-case value is about $21 against a $392 price.

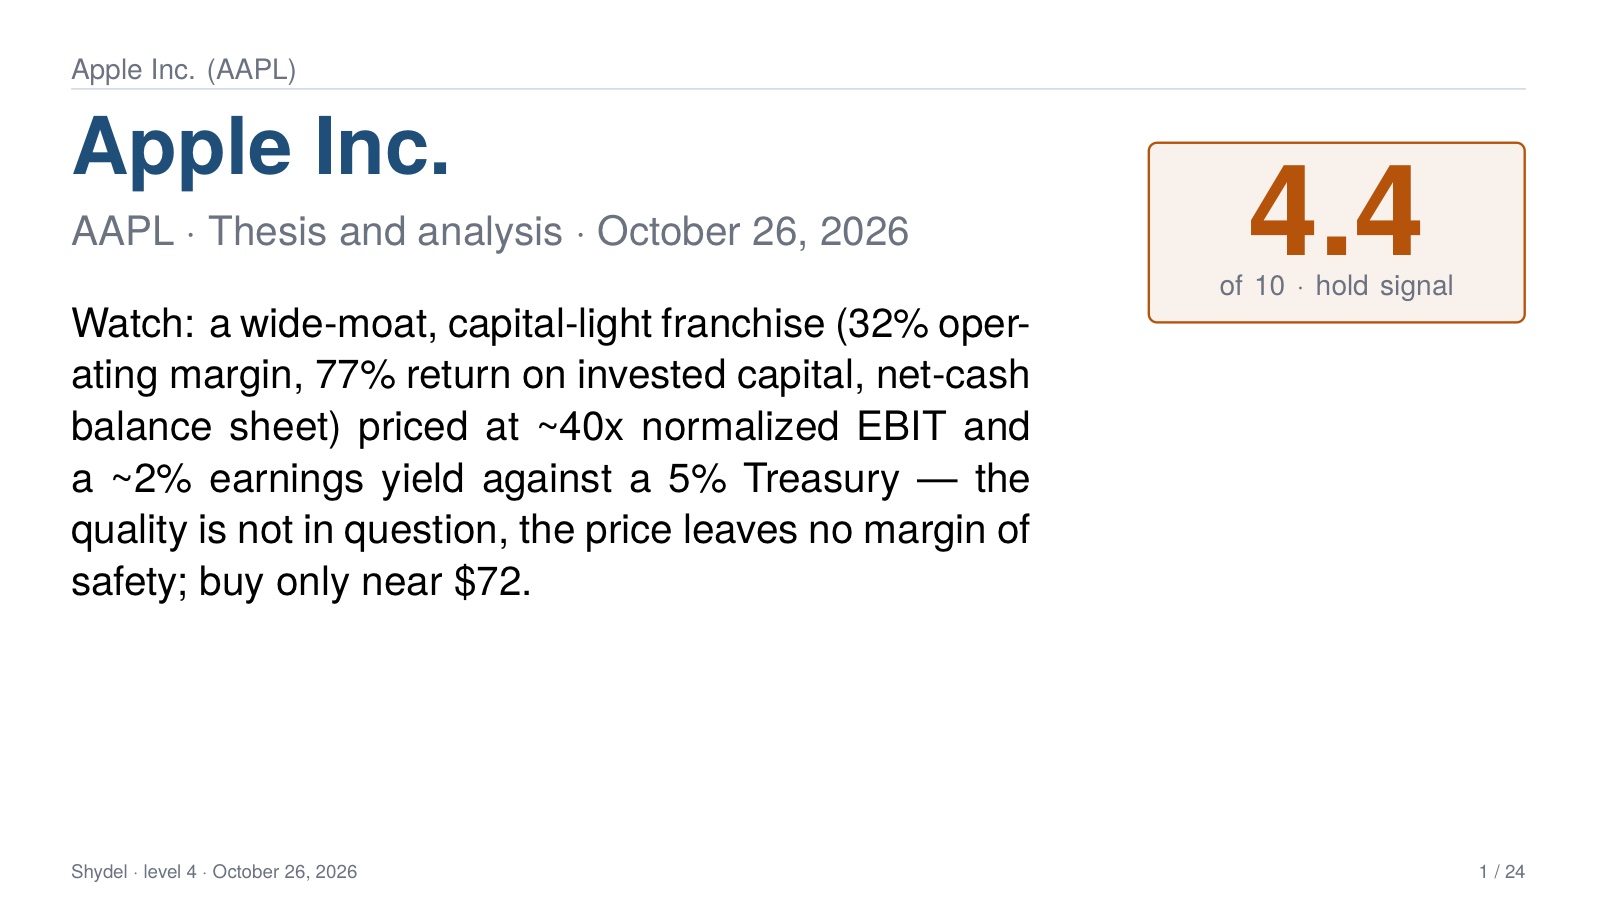
AAPL · AppleWatch

The quality is not in question. The price is.

A wide-moat, capital-light franchise with a 32% operating margin, about 76% return on invested capital and $62 billion of net cash, priced at about 40x normalized EBIT and a 2% earnings yield against a 5% Treasury. Buy only near $72.

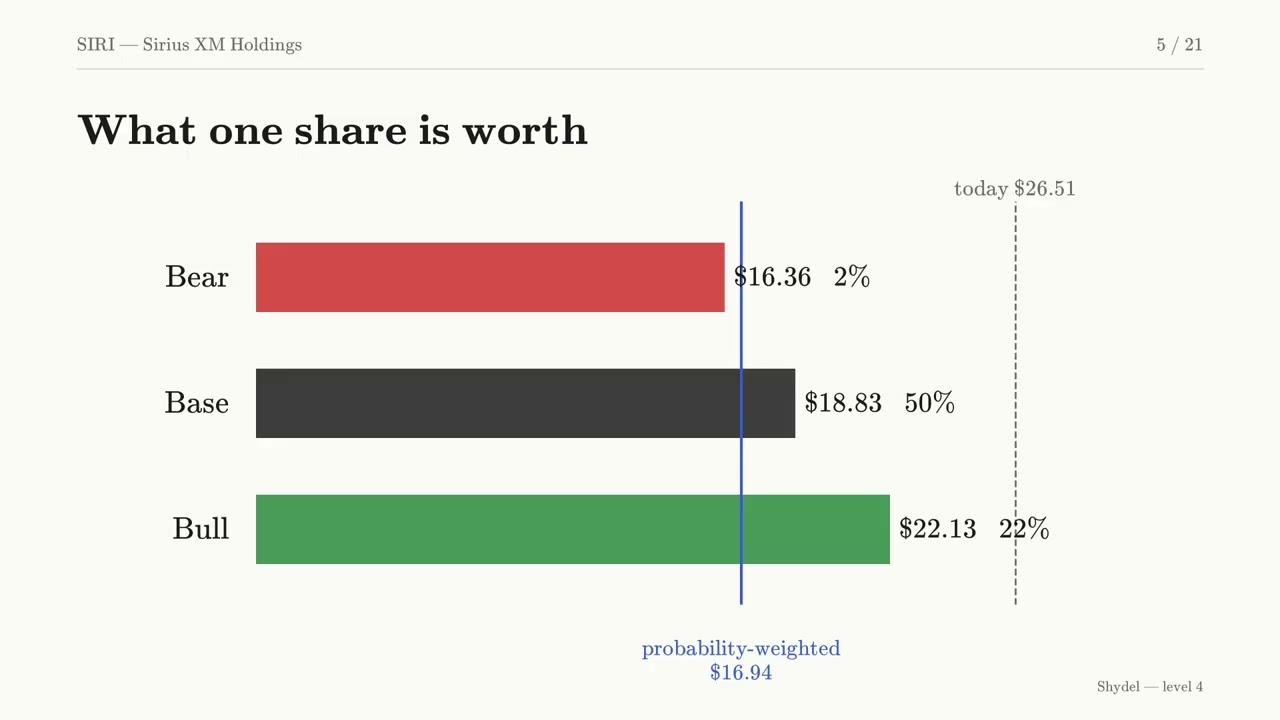
SIRI · SiriusXMTrim

Cheap multiples, no margin of safety.

A high-margin, cash-generative franchise bolted to a slowly melting in-car subscriber base and $9.6 billion of debt. On a cash-flow appraisal the equity is worth less than the price.

FISV · FiservHold

Cheap on the multiples, thin on the margin of safety.

A sticky, 80%-recurring payments and core-banking franchise at about 6x earnings. $29 billion of debt, the Clover litigation and merchant share loss keep it a hold.

QCOM · QualcommTrim

Elite business, wrong price.

A fortress balance sheet and a 30% operating margin, trading above even the bull case. Patent licences up for renewal are the central contingency.

NOMD · Nomad FoodsHold

Cheap frozen-food giant with a debt problem.

Birds Eye, iglo and Findus at under 10x earnings. Recurring "exceptional" charges and 5.5x leverage make the business weaker than the old record claimed.

LULU · LululemonHold

100% return on capital at 5x earnings. Why not buy?

Valued on honest post-tariff margins instead of the pre-tariff peak, the margin of safety is thinner than it looks. Americas comps are the swing factor.

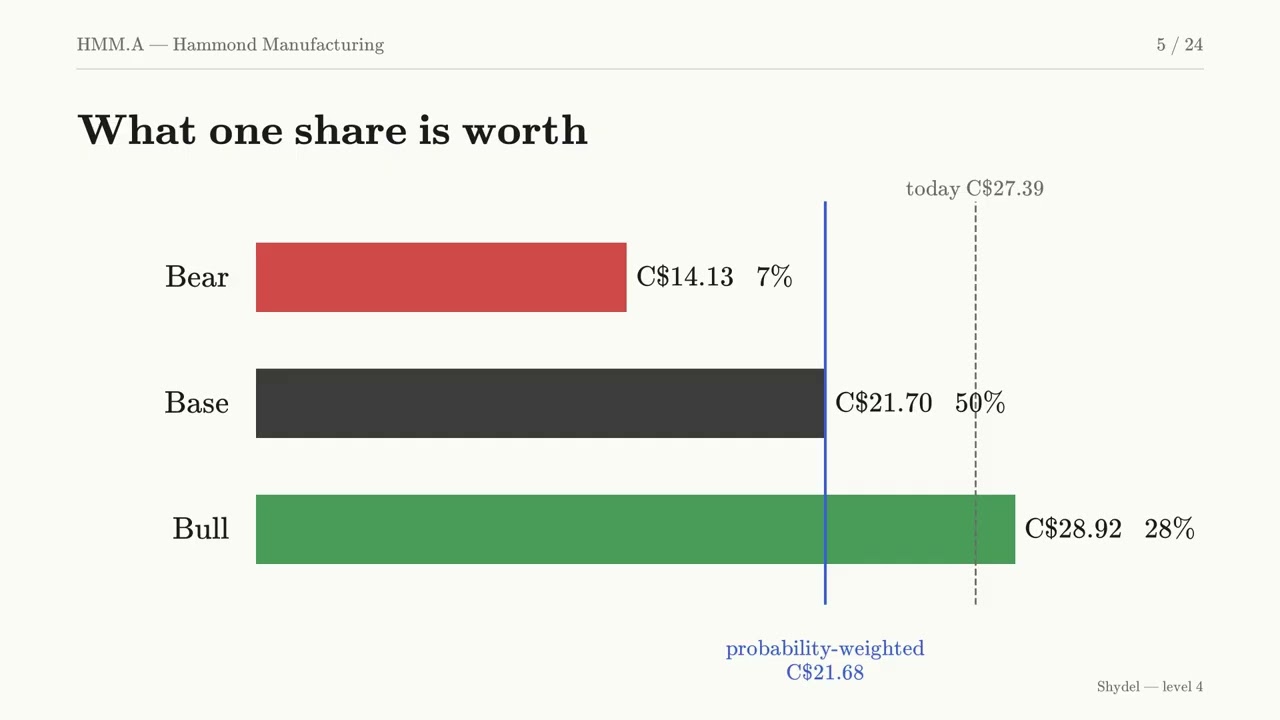
HMM.A · Hammond ManufacturingTrim

A great business we're trimming.

A family-run Canadian microcap earning 22% on tangible capital, riding the datacom build-out. The issue is a 37% single-name concentration with no margin of safety.

CMCSA · ComcastHold

Dirt cheap, but is it a buy?

About 4.5x normalized earnings and $18 billion of free cash flow a year. A real but eroding broadband moat, a geared balance sheet and the NBCUniversal spin as the catalyst.

Want this on your own portfolio?